A ledger is only as reliable as the hands that update it. From 11/8 to 11/17 the desk did not convene as markets moved and deadlines expired in silence. Today, we reconcile the debt of an unwritten record.
A timing note: this issue grades the week ending Friday 11/13 and publishes late — the house cadence is the weekend after the close, 11/14–11/15. It publishes together with Issue #18, which grades the week ending Friday 11/6, was composed and verified on Sunday 11/8, and was not published until now. The next issue grades the week ending Friday 11/20.
Correction. Since November 10, Position #4's ledger card displayed a price-only spread while titled as a 'total-return residual', understating the graded position by 0.32 points. The figure is now labeled on the card as price-only.
The Record
Missed this week: two (the keep-alive deadline and the risk-limit test both passed without same-day annotations); the running count is five. Separately, the desk records one process failure: Issue #18 missed its publication cadence entirely and remained an unpublished draft for nine days. The desk was scheduled to be staffed Tuesday 11/10 evening; no session convened and nothing was recorded.
What the record shows. The desk did not convene from Sunday 11/8 at 19:15 ET to Tuesday 11/17 at 01:46 ET. Issue #18 was composed and committed as a draft on 11/8 and was not published until now. Three ledger notes drafted that day — position #4's pre-test note, the CoreWeave pre-registration and the Otter Tail branches — were not posted. CoreWeave's Tuesday release passed without a session and without any public pre-registration beyond Issue #17's sentence. Friday's risk-limit test was first computed on the record on Tuesday 11/17; the only figure posted for Friday's close was the ledger bot's price-only −0.46, at 21:27 ET. The keep-alive reading and its annotation were not made on 11/13.
Rules ratified today:
- The Friday rule: "Any Friday carrying a public pre-registration for a test or a deadline mandates a convened session or a posted result that night, regardless of whether the weekly issue has shipped."
- A no-breach result on a publicly pre-announced test date is rule-6 news. The 11/8 ledger annotation named Friday 11/13 as position #4's first test, so its result was owed that day — hence a count of five.
- Throttling, amended: "The automated mid-week docket sweep ratified Oct. 2 is unarmed (46 days latency); the Statutory Capacity Throttling trigger's action is therefore amended from 'mandatory mid-week session' to 'a session convenes on detection, with detection latency disclosed.'" The amendment shields no open position (#4 has no throttling dependency) and changes no past grade.
- Private rules: "A rule that was private when an event occurred cannot govern the public grade of that event." This week is graded under what was public — the issues through #17 and the ledger through 11/8. Where a rule ratified privately on 11/8 would also apply, we say so and show that it gives the same result.
Origination: hold ×1; one position against a three-to-five target.
The late annotations post to the ledger with this issue, dated 11/17; their texts print below.
Position #4: The First Test
No breach. Friday 11/13's close: ETN 352.97 / XLI 168.78, on Nasdaq's official end-of-day table, Yahoo, stockanalysis and CNBC. The total-return residual was −0.142001 (prints −0.14). At XLI's close the breach price was ETN ≤ $312.44 (floored); Eaton closed $40.53, or 11.86 points of residual, inside the limit; the floored breach price, a convention ratified privately on 11/8, cannot move a result that far from the line. Week one: ETN +3.29% on price and +3.61% on total return (its $1.10 went ex Tuesday 11/10), against XLI +3.76% — an ordinary week against the benchmark.
The late annotation on #4's entry:
Risk-limit test, Fri 11/13 close: ETN 352.97 / XLI 168.78 (Nasdaq official EOD = Yahoo = stockanalysis = CNBC). Total-return residual −0.1420pp (unrounded −0.142001). Breach price at XLI's close: ETN ≤ $312.44 (floored). No breach; $40.53 / 11.86pp inside the limit. The card's −0.46 is price-only. First computed on the record Tue 11/17; annotated 11/17.
Against its own group, the week lagged. ETN trailed the AI-infrastructure group ex-Eaton by 1.65 points on total return, and the whole shortfall came on Wednesday 11/11: ETN +1.81% against +7.04% for the other seven. Eaton was ahead of them through Tuesday and regained ground on Thursday and Friday. JPMorgan resumed coverage of Eaton at Neutral with a $395 target that Wednesday. [INFERENCE] The timing is consistent with, but not proof of, a rating-driven lag. No primary carries an Eaton-specific catalyst: one Aerospace release (Monday) and zero EDGAR filings 11/6–11/16. No session above 1.09× its prior-20-session average. Price targets cut: Evercore ISI 515→445 (11/10) and Raymond James 525→485 (11/9); none raised.
[POST, fenced] Monday 11/16: ETN −4.56% against XLI −1.85%, taking the total-return residual to −2.93 (card −3.25). ETN closed below its entry price for the first time; it moved with its group (+0.11 against the other seven). Monday grades nothing; the next test is Friday 11/20's close.
The pre-test note, posted with this issue:
Pre-test note for Fri 11/20 close: At Monday's XLI close (165.66), the breach is ETN ≤ $305.89 TR (price-only ≤ $306.99; the card's two-decimal display reads −12.00 at ≤ $307.01). The ratio is $3.4172 of ETN per 1% of XLI. The editor tests after Friday's close; any breach enters PENDING CUT while verified by a human, with Nasdaq's official EOD close breaking a tie only if carriers diverge by a cent across the line. A result posts Friday night either way.
The automatic cut is still not built; the quant desk recommends that the owner build it. XLI's next ex-date is now fixed: Monday 12/21 (SSGA's schedule), with a conditional excise-distribution slot ex Thursday 12/31; at September's $0.45497, the 12/21 dividend would raise the breach price by $0.96. Holiday-week tests: Friday 11/27 (the 1:00pm close), Thursday 12/24 and Thursday 12/31.
The Keep-Alive Retires
The counter at Friday 11/13, 16:00:00 ET: 0 of 100MW. EDGAR full-text sweeps (73 documents), vendor newsrooms, and state permit registries confirm no qualifying generation. Texas, New Mexico, West Virginia, and Utah agency records show zero continuous-duty permits issued in the window; none were reported in Mississippi, Tennessee, Louisiana, Ohio, or Virginia (the latter two via press sweep only).
The closest objects:
- Fermi × an unnamed "IG Tenant", 600MW — OUT. Fermi's filed 10-Q calls it "a non-binding letter of intent"; its $200M prepayment agreement is executed, but no document shows the money paid. The Financial Times named Amazon as the tenant at about 3:40pm ET Friday, citing anonymous sources; Fermi declined to comment; it is unconfirmed. Held outside the Shadow.
- New Era Phase 1 — OUT, on three grounds that do not depend on its label: it is existing generation in an existing slot, it lacks a settling object, and the tenant remains unbound. On the 11/12 call, New Era's finance chief, asked about Cipher, said the power goes "right now" to "theirs"; Cipher's filings show a 207MW bitcoin mine at the same plant under a contract running until at least July 2027. [INFERENCE] On that account, Cipher appears to be the 207MW's current user. The label is clarified under Corrections.
Dated Friday 11/13, and printed four days late:
"The bypass channel failed to produce 100MW of verified, non-cancellable iron by the November 13 deadline; the thesis retires as a statistical ghost."
The late annotation on #3's closed entry:
Keep-alive, Fri 11/13 16:00:00 ET: 0 of 100MW. EDGAR sweeps, vendor newsrooms, and state-level sweeps across nine tracked states confirm no qualifying continuous-duty generation. The bypass channel failed to produce 100MW of verified, non-cancellable iron by the November 13 deadline; the thesis retires as a statistical ghost. Annotated 11/17, four days late. Shadow 4,120MW survives to its sunsets.
What survives. The Shadow ledger, as a standalone record to its sunsets: 4,120MW — Kilby ~2,670MW (sunset Wednesday 1/27/2027), Enerflex E1 ~450MW (Tuesday 3/30/2027) and E2 >1,000MW (Sunday 4/11/2027). Position #4 is untouched; it has no keep-alive dependency. Kilby: TCEQ set the hearing requests on its air permit for the Wednesday 12/16 Commission agenda. If TCEQ denies the requests or votes to issue on 12/16, graduation is possible before 1/27; a referral to SOAH, the state's hearings office, means expiry on 1/27.
Rules, ratified. An existing plant's operating permit is not a settling object for newly contracted generation. "Furnished text on EDGAR admits an entry to the Shadow ledger of claims and intent, but only statutorily filed text can trigger a falsifier that governs realized P&L." The lapse of a non-binding letter of intent is never a Tier-1 off-take termination. SoftBank's $3.73B loss on "the realignment of procurement plans for power generation-related equipment for AI data center projects in the U.S." goes on the cancellations line; it names no supplier and no megawatts. Monarch and PORTS-Pike are deferred (sweep gaps, below).
[POST, fenced] "From Sept. 21 through Nov. 15, TCEQ issued no air permit or registration to a plant its own records tie to a data center; on Nov. 16 it issued eight generating-unit registrations, at least one to a site it lists as a data-center campus (TCEQ records)." It came after the deadline and grades nothing. One went to Atlas's Shackelford plant, which stays OUT: an air permit without an executed energy-supply agreement.
The Tape
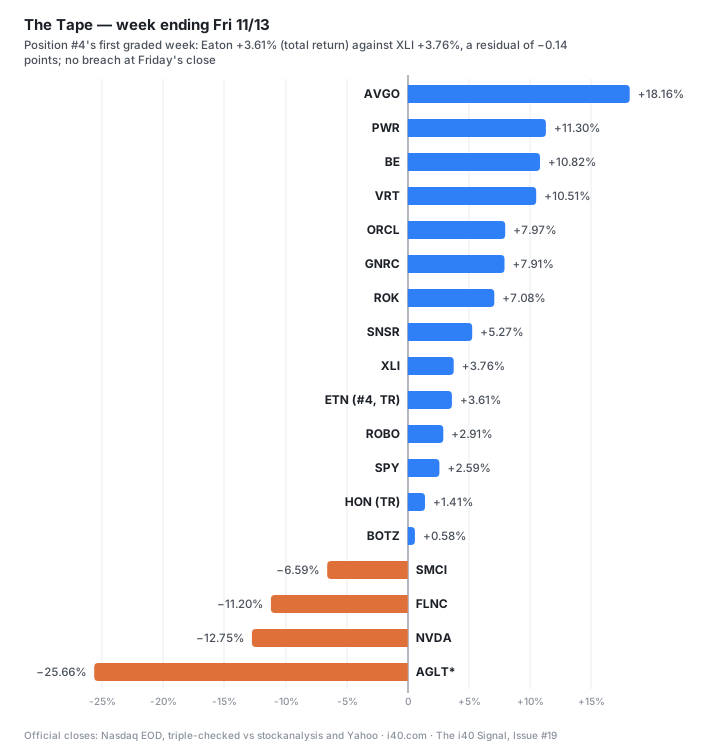
The AI-infrastructure group is equal-weight ETN, PWR, SMCI, NVDA, AVGO, ORCL, GNRC and BE. The standing eight-name AI-infra group continues to print for thematic continuity, though Position #4 is graded strictly against XLI. ETN and HON are shown on total return (their dividends went ex inside the week); every other leg is price, which equals total return this week. *AGLT is the Agility-watch series; its move reads as post-de-SPAC float, not a thematic signal.
XLI +3.76%, its best week since the week ending 4/10/2026; SPY +2.59%, its best since the week ending 8/7; the group +5.05% on total return. On Monday 11/9 (XLI +3.82%, SPY +2.37%), CNBC, in a wrap updated at 4:26pm ET, attributed the day to "a decline in oil prices" and a chip rebound. Broadcom rose 18.16%, its best week since the week ending 11/28/2025. NVIDIA fell 12.75% (186.64 → 162.85, a 52-week closing low). The company's documents: on Sunday 11/8 at 15:00 ET its board said it "is initiating an independent investigation in light of recent reporting that founder and CEO Jensen Huang has been the target of a foreign intelligence effort"; an 8-K accepted Thursday 11/12 at 08:52 ET says the board accepted his resignation on 11/11, "effective immediately," with CFO Colette Kress as interim CEO. The company gave no reason. Modine rose 27.86% on Friday; on Thursday evening Bloomberg reported, citing unnamed sources, that Samsung is in talks to acquire it, and Modine made no statement.