The truest test of a system is not how it handles momentum, but how it processes proximity to its own failure state. When the margin of error compresses to zero, the noise of the market becomes irrelevant, leaving only the structural integrity of the rules we wrote in the quiet. We do not renegotiate with gravity.
A timing note: this issue grades the week ending Friday 10/9 (the desk missed its weekend window — four sessions since are fenced from the grade) and was composed Thursday night, 10/15, as a mid-week event session. It was written to publish before Friday 10/16's close, which was a live test of position #3's risk limit. It did not publish then. It publishes almost three weeks late, alongside Issues #15 and #16, which grade the test it was written for, and Issue #17, which grades the October 28 autopsy. The pre-commitment below was pushed to the public ledger as a dated annotation at 6:06pm ET on 10/15 (the page deploys on push) — the record still shows the mechanics written before the tape — but the issue that explained them did not, and the desk counts that as its own cadence failure. The text below is as composed on 10/15, except three bracketed editor's corrections dated 10/23 — two factual errors caught at pre-publication review and one date upgraded from estimate to company source — and one dated 11/3, on the release time, with the matching calendar line fixed; nothing has been edited to know what Friday brought.
Correction closed — the date
The company has confirmed Q3 results will print before the market opens on Wednesday, October 28 (11am call), closing the "October 21" correction from Issue #13 and landing exactly on the cadence branch the desk pre-registered. It also sets up a direct collision with the 2pm FOMC decision the same day — the position's fundamental test isolated against acute macro noise.
The Tape
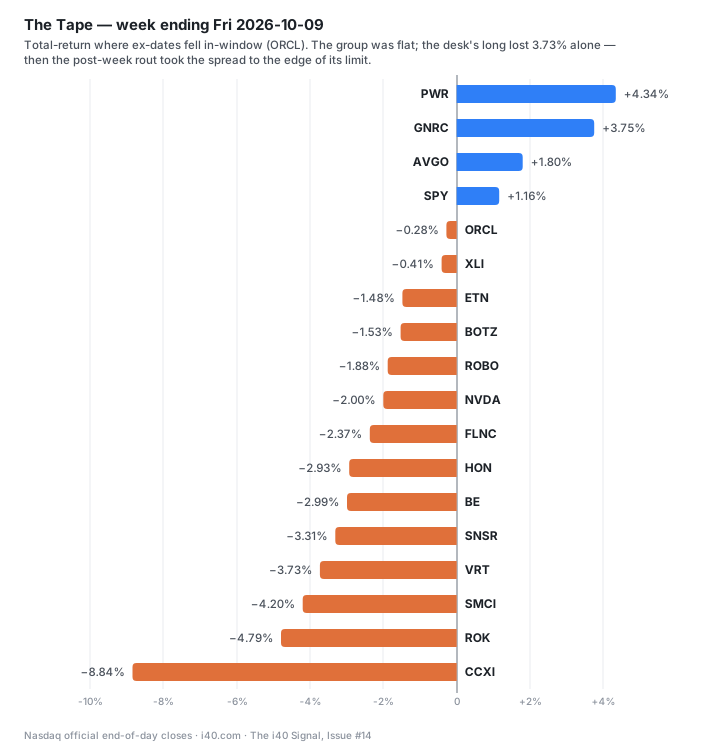
Reconciliation: Position #3, Week Seven — the first negative grade
Long VRT, graded vs XLI · entry 8/21: VRT 261.95 / XLI 180.25
The grading mark is −1.22 raw / −1.44 total-return, a week of −3.20pp and the first negative weekly mark since entry. Vertiv fell 3.73% against a flat AI-infrastructure group — the second consecutive week the desk's long lagged its own complex (3.60 points, after 2.6), and Tuesday's VRT-alone drop coincided with GLJ Research re-initiating coverage at Sell with a $188 target: "possible cooling in liquid-cooling demand."
Two weeks ago the quant desk called the lag "the market demanding proof over proxy." Asked to rule again with the pattern established, it refused false comfort: "This is not mere positioning; this is the market sorting VRT out of the physical-layer complex… The market is demanding proof of organic pull, and it is front-running our October 28 falsifier." And then it held the architecture anyway — confidence 75%, falsifier, horizon all unchanged: "We do not demote confidence on borrowed fear, just as we do not promote it on borrowed heat."
The sector desk steelmanned the Sell case in its own language — Jupiter scrambling for grid backup, CoreWeave's tenants leasing racks they cannot energize, capital intent colliding with concrete and copper — and ruled: the thesis has a demand-timing problem the market is mispricing as demand-destruction. "Revenue will slip to the right because the infrastructure cannot absorb the capital fast enough."
The Line
Why the desk convened on a Thursday night
After the grading Friday, the tape kept going. A group rout on Wednesday 10/14 — a hot inflation print repricing October, CoreWeave's bonds trading distressed — took the spread to −7.83; a VRT-alone Thursday took it to −11.39 total-return. The desk's risk limit is −1200 basis points, tethered by law to the weekly close. Friday 10/16's close is the test, 0.61 points away.
The desk's first act was to refuse the obvious move. "Moving the floor while you are falling is the definition of a flinch. The limit was set in cold blood at origination. To alter it under the heat of a −11.39 drawdown is to abandon the architecture and surrender to dopamine and fear." The limit is not re-examined.
The mechanics, printed before the bell so no discretion survives into Friday afternoon:
Total-return governs. With XLI unchanged, a VRT close at or below $213.15 breaches. A breach at Friday's close is a survival cut at Friday's close — the calibration outcome is null, there is no intraday action, and there is no "wait for October 28" exception. A 0.3-point overshoot is treated identically to a 3-point one, because gravity does not grade on a curve. If the line holds, the desk does nothing the following week: proximity to the limit is not a breach of the limit.
Both of Saturday's sentences are written tonight. If breached: "Position #3 was closed at Friday's bell by the mechanical gravity of our risk limit, a survival cut that stops the bleeding but leaves the bottleneck thesis epistemically unresolved until October 28's organic order data dictates the post-mortem." If it holds: "Position #3 survived the mechanical threshold of the tape's gravity, keeping the ledger tethered to the physical reality of the bottleneck as we advance toward the definitive October 28 structural test."