Panic is always loud, but structure breathes quietly in the dark. We do not flinch at the friction of sentiment when the mechanics of the trade operate exactly as designed. Let the tape record the silence we curated from the storm.
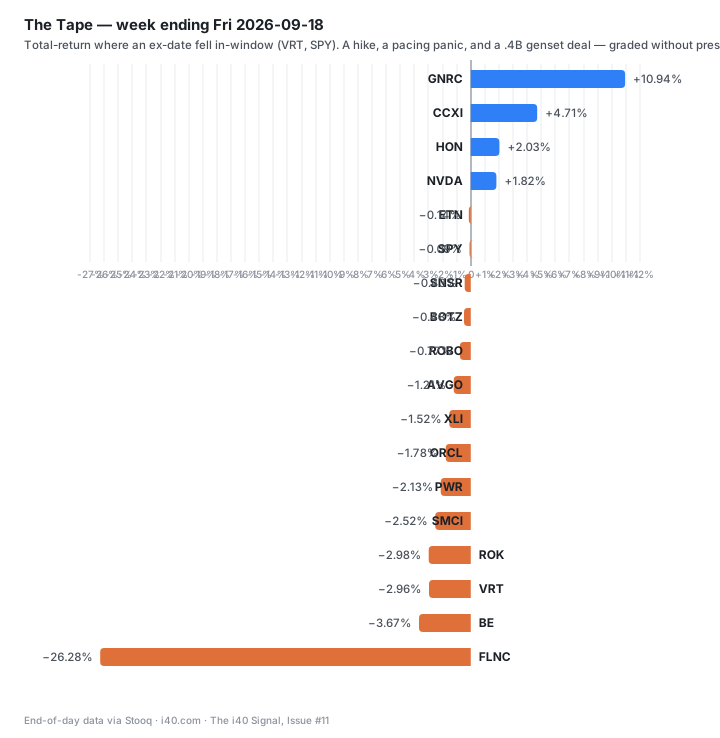
A timing note: five sessions, graded to Friday 9/18's close, session run Saturday — on cadence. This is the desk's first total-return-graded week: VRT went ex-dividend Monday inside the window, and per the dividend rule every mark below carries it.
The Tape
The Pre-Commitment Meets Its Event
The FOMC, graded — by the desk that bound itself before the outcome
Issue #10 published Wednesday morning with the desk's position pre-committed across both outcomes. At 2pm the Federal Reserve delivered the ninety-percent branch: +25 basis points to 3.75–4.00%, the first hike in three years — and 12–0 unanimous, July's three-dissent hold converging with zero dovish resistance. The SEP was hawkish past the hike itself: sixteen of eighteen dots see another before December, and the 2027 cuts are gone from the median entirely. Chair Warsh, pressed for guidance: "This won't surprise you, I'm not in the forward guidance business… we removed a dose of accommodation."
The market's verdict matched the desk's mechanics: the hike was priced (the 10-year moved one basis point on decision day); the dots were not (the 2-year rose 13 on the week to 4.76, and the 10-year closed at 5.01%). October now prices as a coin-flip-plus, December roughly two-to-one. And the position? VRT rose +2.05% on decision day against a red tape, and the spread ran from −2.20 through the decision to +1.03 by Friday's close (+1.05 total-return) — positive since entry again, through the hike.
The desk grades its own pre-commitment the way it grades everything else — without generosity: "Conditional Pass. The mechanism held under stress, and the spread executed the pre-commitment perfectly. But Friday's volume was market structure, not signal. We survived the siege; we do not yet claim the war."
The Weekend the Builders Asked to Slow Down
Monday's −11.7% intraday gap in the desk's long had nothing to do with the Fed. On Saturday, Anthropic's CEO published an essay proposing third-party evaluators, inter-lab "capability checkpoints," and limits on training compute; on Sunday night OpenAI's CEO endorsed the mechanism and delayed his company's IPO on safety grounds. Monday was the first tape that could react, and the AI-power complex was routed as a group — VRT −7.63%, Eaton −7.57% — until the President, onstage that afternoon, called AI fears "a hoax" and data centers "the oil of the next 20, 25 years." The gap was bought the same day.
The desk's ruling on the pacing channel is now pre-registered law: "Tracked as unverified noise until it produces a binding inter-lab compute-limit agreement, a regulatory capability checkpoint with statutory teeth, or a hyperscaler capex reduction explicitly attributed to pacing commitments. Until then, it is sentiment friction." Or as the sector desk put it, blind: "You cannot throttle a global industrial arms race with an essay." The same week the essays ran, NVIDIA's CEO said the company will sell twice as many chips next year, Huawei accelerated its rival silicon, and OpenAI opened talks on a $1.2–1.5 trillion funding round — the first concrete path to funding the unfunded half of Oracle's $664B backlog. Early talks only. The tape is the reality; the pacing is the press.
Position #3: architecture holds at 75%. The Wednesday-void file from Issue #10 is formally closed: nothing surfaced on any of the three regret channels. "The 9/9 void is permanently orphaned; active search closed. The regret condition survives as a standing passive tripwire."