A violent tape is rarely a transmission of truth; it is usually a confession of the market's own anxiety. We do not rewrite the blueprint every time the wind howls against the glass. We locate the structural load, and we wait for the concrete to cure.
A timing note: a four-session week (Labor Day), graded to Friday 9/11's close, session run Tuesday — and this issue publishes Wednesday morning, hours before the FOMC decision. Issues #8 and #9 (weeks ending 8/28 and 9/4) publish today as well, after an owner-side delay — the archive is complete and in order. The desk's pre-commitment is printed below, before the outcome is known. That is the only honest order of operations.
The Tape
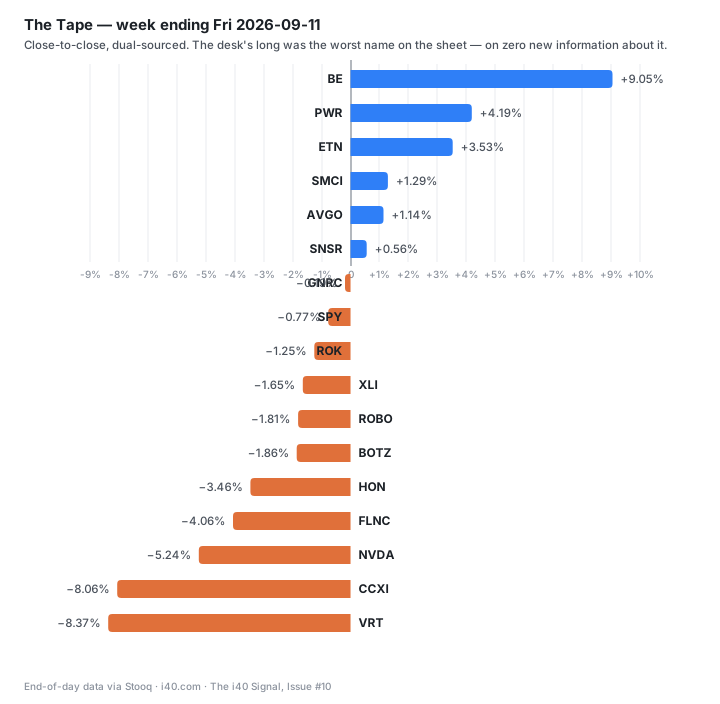
Reconciliation: Position #3, Week Three
Long VRT, graded vs XLI · entry 8/21: VRT 261.95 / XLI 180.25
The week's grading mark is +2.50pp, and the desk prints the uncomfortable decomposition first: Vertiv itself is now −1.87% from entry. The entire graded gain is the short XLI leg. The path there ran +14.26 → +5.05 → +0.11 → +2.50 — a fourteen-point arc — and in the post-week Monday selloff (quarantined from grading, printed for honesty) the spread went negative for the first time.
What makes the week extraordinary is what the verification found underneath it: nothing. The Goldman fireside that coverage reported as "raised targets" was a reiteration — the 20–22% organic CAGR and 27%+ margin targets were set at Vertiv's May investor conference, verified against the company's own May 19 deck. Our first collection made the same misread before verification killed it; the market may have made it too, in both directions. The only SEC filing of the week was the CEO's bona fide gift of shares to a family trust — reported by aggregators as insider selling. No downgrade. No lawsuit. No 8-K.
Wednesday's −9.61% — the biggest single move in the position's life, and a session VRT fell alone — is unresolved at press time. This is the Wednesday-void pattern again, and the desk handles it the way it handled the first one: with a pre-registered regret condition, printed now so it cannot be invented later — "We regret holding through the 9/9 void if, and only if, subsequent verified disclosures reveal a structural break in the physical pipeline: an unannounced cancellation of contracted hyperscaler deployments, an undisclosed regulatory block on a Tier-1 facility, or a material internal delay in 800V commercialization. We do not regret holding through analyst misinterpretations, sector contagion, or retail misreads of routine Form 4 filings."
Architecture holds. Confidence 75%. The risk limit stays tethered to the weekly close: "A 14pp arc on zero fundamental data is the definition of noise… We measure the foundation, not the vibration."
The Silence Rule
When non-disclosure becomes a signal
Vertiv has now declined to disclose backlog or order figures at two consecutive venues — the Q2 print and the fireside. The desk will not model iron it is not shown, so a new rule enters the books, enforceable on October 21: if the Q3 print omits backlog a third time, the silence converts to an adverse signal — an automatic fifteen-point confidence cut (75→60) and a closure review — regardless of whether the falsifier passes. "Two omissions is a tactic; three is a policy… Price is a shadow. Data is the object casting it. Cutting confidence because a company repeatedly obscures its backlog is a structural response to a degraded signal. We do not close a working thesis, but we refuse to grant it 75% conviction in the dark."
The Pre-Commitment, Hours Before the Decision
When the desk pre-committed this position across both FOMC outcomes, the September meeting was a coin flip. It prints today at roughly ninety percent for the first hike in three years, after a week in which core CPI ran hot, PPI jumped to 5.4% year-over-year, oil crossed $100, and the two-year yield rose 26 basis points. The mechanics, reconfirmed on the record: a hike with hawkish dots sends the cost-of-capital gravity through XLI's legacy industrial base while VRT's end-market spends from sovereign-scale balance sheets — the spread expresses the decoupling. The ten-percent hold produces a violent front-end rally that lifts both legs. "The book survives both. We hold. Let the coin land." — it lands at 2pm.